Hamilton-Jacobi-Bellman Equation
Software / App
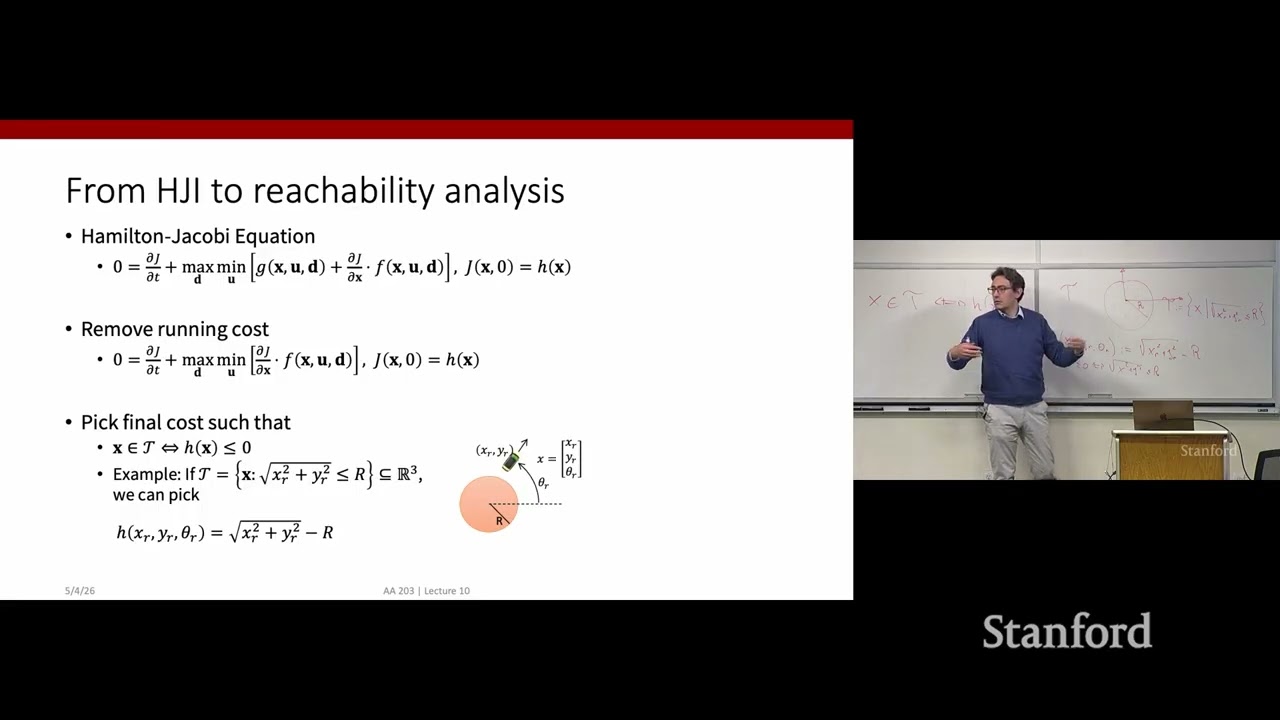
The formalism for solving differential games and computing backward reachable sets, by setting the running cost to zero and defining the final cost to represent set membership.
Mentioned in 2 videos
Save the 2 videos on Hamilton-Jacobi-Bellman Equation to your own pod.
Sign up free to keep building your knowledge base on Hamilton-Jacobi-Bellman Equation as more episodes are added.
Videos Mentioning Hamilton-Jacobi-Bellman Equation

Stanford AA274A Principles of Robotic Autonomy | Autumn 2019 | Decision Making Under Uncertainty
Stanford Online
The continuous-time equivalent of the dynamic programming principle.
Stanford AA203 Optimal and Learning-Based Control | Spring 2026 | Lecture 11: Introduction to MPC
Stanford Online
The formalism for solving differential games and computing backward reachable sets, by setting the running cost to zero and defining the final cost to represent set membership.